Australia / Housing finance
Victoria’s average loan grew. Its state rank fell.
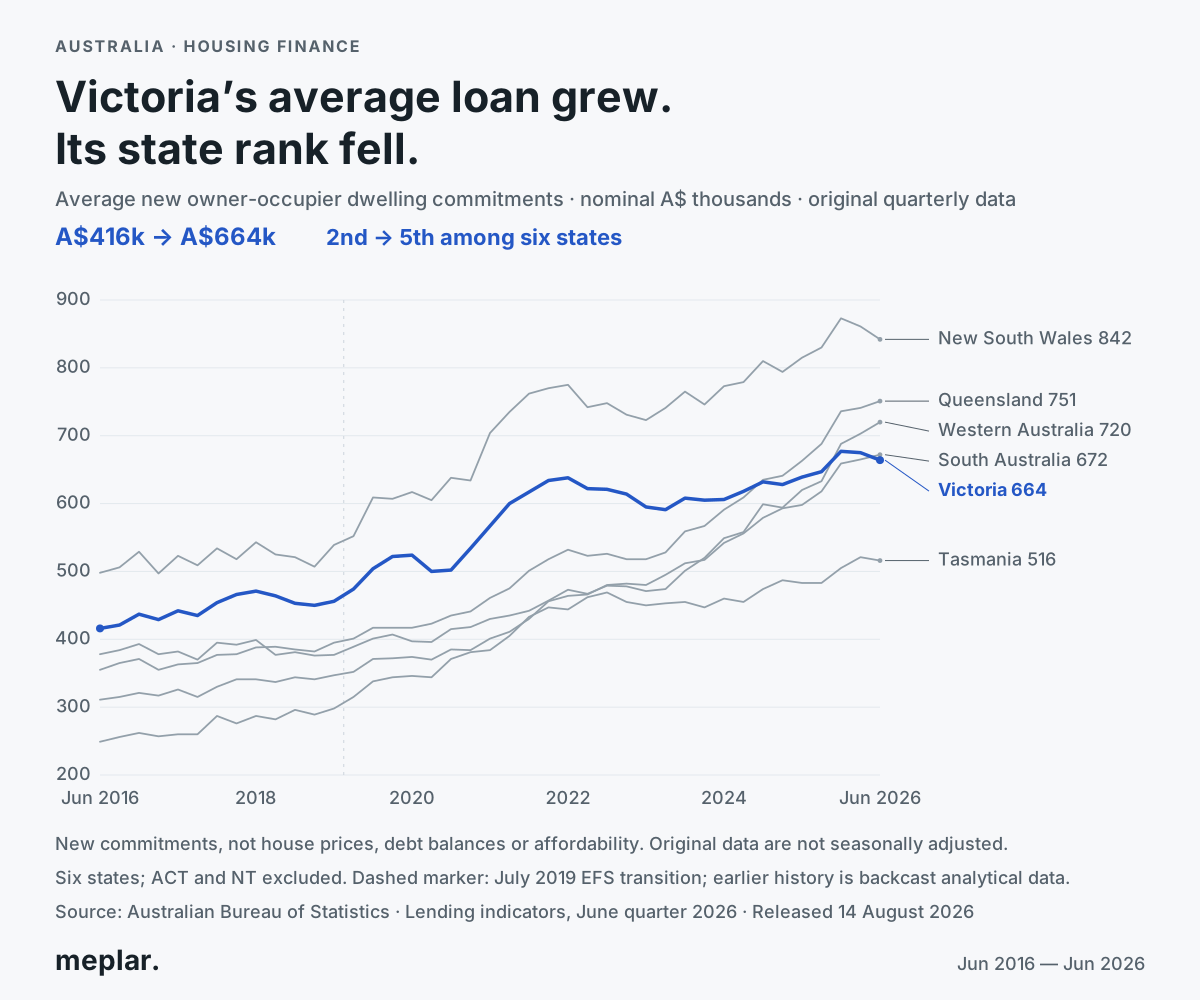
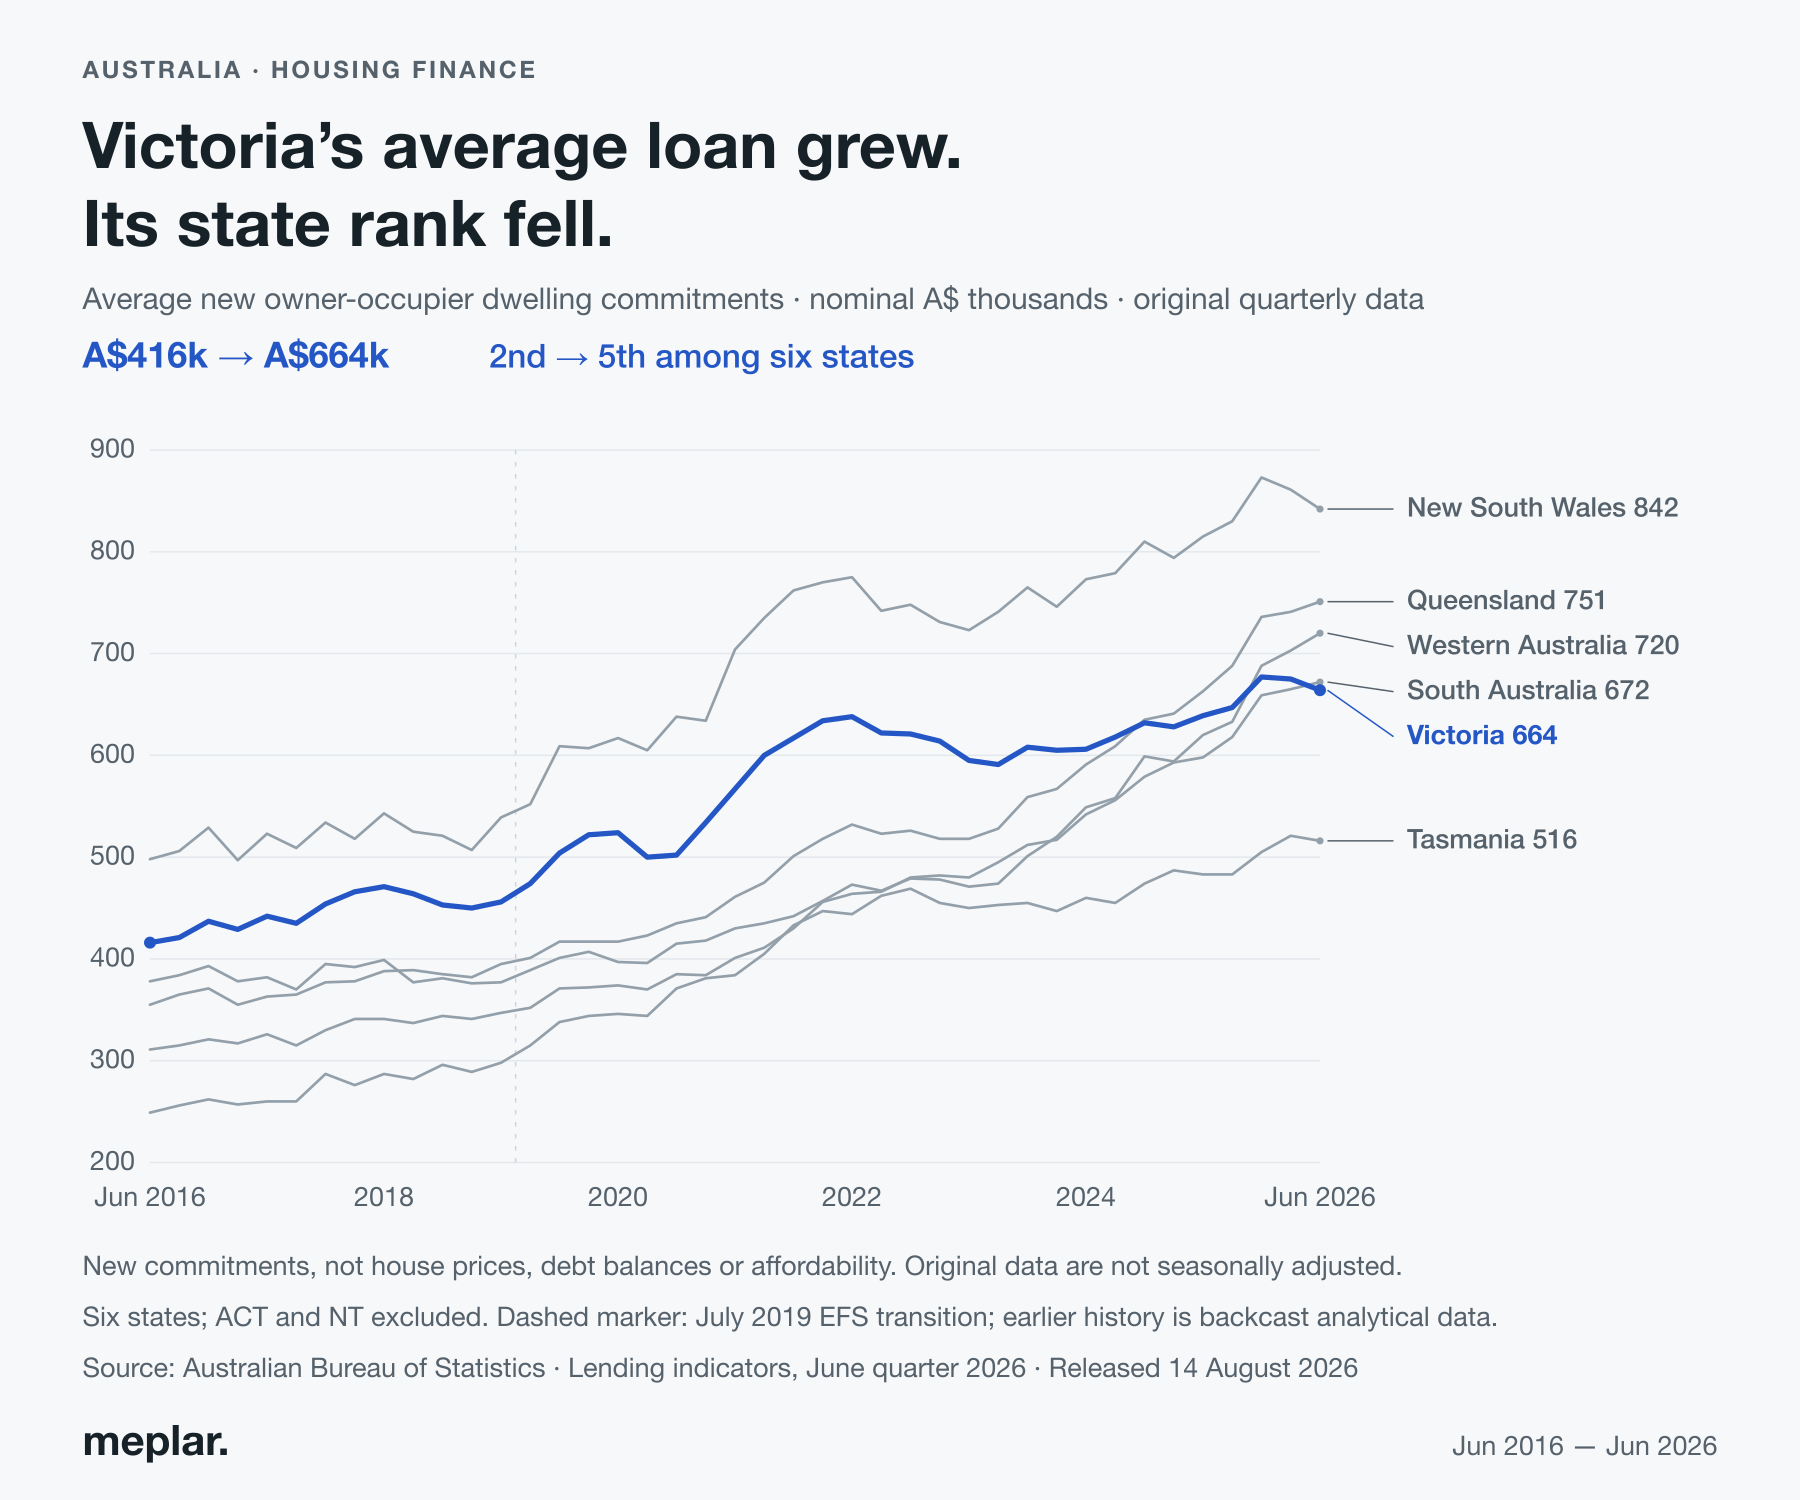
Victoria’s average new owner-occupier dwelling loan commitment rose from A$416k in June quarter 2016 to A$664k in June quarter 2026, while its rank among Australia’s six states moved from second to fifth.
A rise in size; a change in order.
In June quarter 2016, Victoria’s A$416k average was below only New South Wales among the six states. By June quarter 2026, Queensland, Western Australia and South Australia were also above Victoria.
South Australia’s latest average was A$672k, just above Victoria’s A$664k. Tasmania remained below Victoria at A$516k. This is a comparison of published averages, not a ranking of household affordability.
The six-state scope matters
The chart excludes ACT and NT. Their source values remain available in the download. Original means not seasonally adjusted; earlier history includes ABS backcasting.
Both endpoints, all six states
| State | Jun 2016 | Jun 2026 |
|---|---|---|
| New South Wales | A$498k | A$842k |
| Queensland | A$355k | A$751k |
| Western Australia | A$378k | A$720k |
| South Australia | A$311k | A$672k |
| Victoria | A$416k | A$664k |
| Tasmania | A$249k | A$516k |
Ordered by June 2026 average. Victoria’s six-state rank: second → fifth.
Source & method
Source: Australian Bureau of Statistics, Lending indicators, June Quarter 2026. The “Average loan sizes for owner occupier dwellings, original, by state” table supplies 41 quarterly averages per geography, from June quarter 2016 through June quarter 2026. Values are nominal Australian dollars in thousands, retained at published precision. The source release is 14 August 2026; our frozen captures were retrieved on 22 October 2026.
The chart selects NSW, Victoria, Queensland, South Australia, Western Australia and Tasmania. It ranks each quarter’s six values from largest to smallest. Australia, the Northern Territory and the Australian Capital Territory are retained in the source extract but excluded from the chart and its six-state rankings. Equal values share a rank. The original averages are copied directly; we do not calculate a new quarterly mean or splice historical releases.
The ABS methodology describes borrower-accepted new commitments, rather than outstanding debt. Dwelling commitments exclude refinancing and cover construction and the purchase of new or existing dwellings; residential land and alterations/additions are separate. Original data are not seasonally adjusted.
Backcast history & interpretation
ABS introduced its EFS collection in July 2019. Where concepts were sufficiently similar, earlier historical series were backcast using the parallel collection period. ABS describes earlier lower-level series as modelled analytical history to be used with caution. The dashed chart marker indicates that transition, not an asserted statistical break.
These are nominal loan commitment averages, not house prices, outstanding loan balances, affordability or an account of causes. Changes in borrower and dwelling mix can change averages. Rank is relative: Victoria’s published average increased between the endpoints even though its position fell.
The June 2026 ACT value is A$666k, slightly above Victoria’s A$664k. Including territories would change the ranking universe; this chart explicitly compares only the six states.
Data access & reuse
The downloads preserve all 369 values across the nine source geographies, 246 charted state values and a six-state rank for each quarter. No chart values are missing. A standard-library Python script rebuilds four CSVs offline from frozen HTML and checks every value against the embedded chart JSON.
Source data: © Commonwealth of Australia, Australian Bureau of Statistics, CC BY 4.0, subject to ABS exceptions. Extracted and visualised by Meplar. No ABS logo or endorsement is used. See source terms.
Take a closer look.
Vector chart, high-resolution desktop and mobile images, quarterly data and frozen source package.